 how-to
Competitive Trade-In Valuations for Vehicle Financing
Table of Contents
- How Dealerships Value Trade-Ins: The Appraisal Process Explained
- Trade-In Equity and Auto Loan: How Your Payoff Changes the Deal
- Using a Used Car Trade-In Value Estimator Before You Shop
- How to Negotiate a Trade-In Value That Reflects the Market
- A Step-by-Step Method for Comparing Competing Trade-In Offers
- Step 1: Lock Down Your Payoff Quote
- Step 2: Collect at Least Two Written Appraisals
- Step 3: Read the Conditions on Each Offer
- Step 4: Note Each Offer's Expiration Date
- Step 5: Subtract Payoff to Get Net Equity
- Step 6: Compare the Total Deal, Not Just the Trade
- Step 7: Confirm Which Offer Is Tied to Dealer Financing
- Step 8: Choose the Highest Net Deal
- How Trade Equity Changes Your Financing Costs
- Taxes, Fees, and Offer Conditions That Affect Net Trade-In Value
- Frequently Asked Questions
Last Updated: October 21, 2026
How Dealerships Value Trade-Ins: The Appraisal Process Explained
A trade-in appraisal is a dealership's estimate of what your vehicle is worth as a wholesale asset, not what it will sell for on the lot. At Rusty Eck Ford, we walk every customer through it before a single number gets discussed, because competitive trade-in valuations for used vehicles for vehicle financing start with understanding what the appraiser is actually measuring.
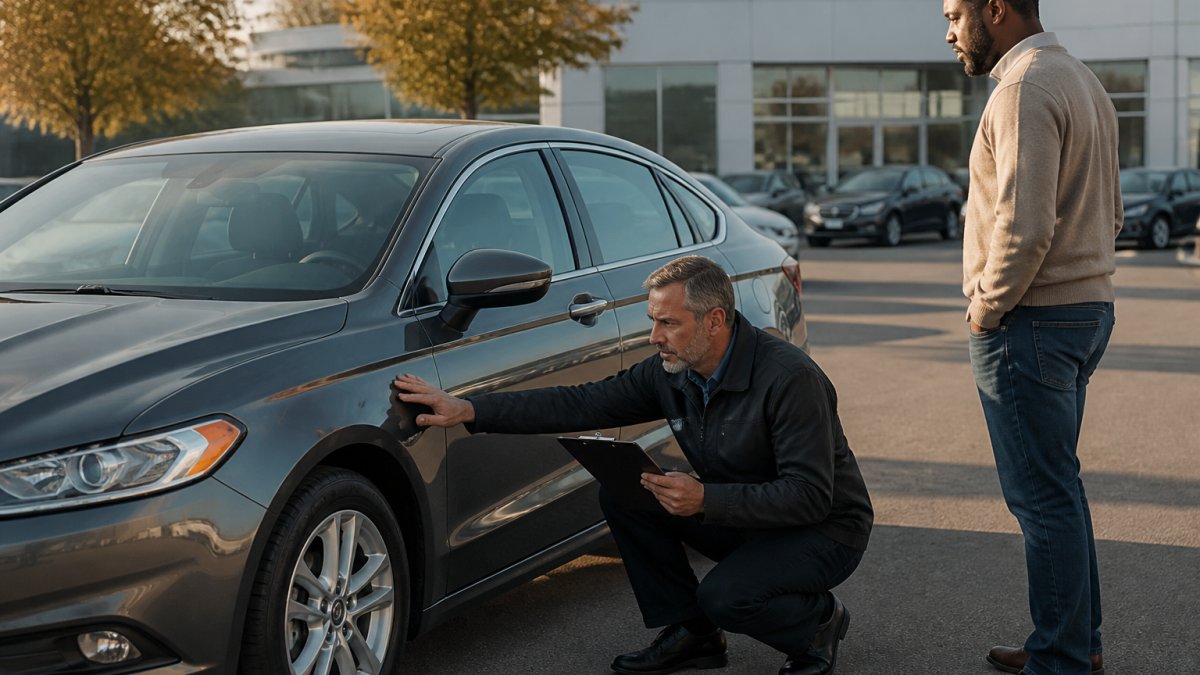
Here is the short version of how it works:
- The appraiser checks the vehicle's condition and history
- They compare it to similar vehicles selling at auction
- They subtract reconditioning costs
The Federal Trade Commission's guidance on vehicle shopping notes that buyers who research their trade-in value before visiting a dealer tend to be better prepared for the conversation. That preparation matters more than most people realize.
Wholesale Value, Reconditioning Costs, and Local Market Demand
Wholesale value is what a dealer could realistically get for your car at auction or from another dealer. It is almost always lower than private-party resale value, and that difference is normal, not a trick.
Three things move that number:
- Reconditioning costs: tires, brakes, paint, detailing. A car needing work gets a lower offer.
- Local market demand: trucks and SUVs move faster in some markets than sedans.
- Inventory levels: if the lot is already full of your model, the offer reflects that.
What Appraisers Inspect and How Condition Affects the Offer
Appraisers look at far more than a quick walkaround. Expect a close check of:
- Mileage and model year
- Accident and service history
- Tire tread and brake condition
A common mistake is skipping a wash and interior clean before the appraisal. It sounds minor, but a clean car reads as a cared-for car, and that shifts the conversation.
Trade-In Equity and Auto Loan: How Your Payoff Changes the Deal
Trade-in equity is the difference between your vehicle's appraised value and what you still owe on the loan.
This is where the trade-in equity and auto loan relationship gets interesting. Your payoff quote, not your monthly payment, is the number that matters.
The FTC's explanation of negative equity in auto trade-ins warns that a dealer's promise to "pay off" your loan does not necessarily erase the debt.
Positive Equity vs. Negative Equity on a Financed Vehicle
- Positive equity: your car is worth more than the payoff. That difference can go toward a down payment.
- Negative equity: you owe more than the car is worth. That amount typically gets rolled into the new loan.
- Break-even: the offer roughly matches the payoff.
Rolling negative equity into a new loan raises the amount financed (Auto Trade-Ins and Negative Equity: When You Owe More than Your Car is Worth). That usually means a higher monthly payment or a longer term, and a longer term means more total interest.
Using a Used Car Trade-In Value Estimator Before You Shop
A used car trade-in value estimator gives you a starting range, not a final number. Use it to set expectations, then treat the in-person appraisal as the real conversation.
Online tools typically ask for:
- Make, model, trim, and model year
- Mileage
- Condition category
Run two or three estimators and write down the range. If a dealer's offer lands well below every estimate, ask what specific factors drove it down.
How to Negotiate a Trade-In Value That Reflects the Market
The strongest negotiation tool is a competing offer in writing. When you know how to negotiate a trade-in value, you stop arguing about feelings and start comparing documents.
Try these moves:
- Get your payoff quote before you shop
- Bring service records and a clean vehicle
- Ask for the appraisal breakdown in writing
A common mistake is negotiating the trade and the new vehicle price as one lump sum. Dealers can shift numbers between the two, and you lose visibility.
A Step-by-Step Method for Comparing Competing Trade-In Offers
Comparing offers properly means comparing net equity, not headline trade numbers. A higher trade figure can still be the weaker deal once payoff timing, fees, and conditions are counted. Here is the method we recommend, with the mechanics behind each step.
Step 1: Lock Down Your Payoff Quote
Request a written payoff quote from your lender that shows the good-through date. Interest accrues daily, so a quote from last week is already stale. Use the payoff figure that will be current on the day the dealer pays off the loan, not the day you get the appraisal.
Step 2: Collect at Least Two Written Appraisals
Verbal offers are not comparable because they cannot be verified later. Ask each dealer for the offer in writing, including the vehicle description, the offer amount, and any conditions. Two written offers give you a real comparison; three give you a fallback if one expires.
Step 3: Read the Conditions on Each Offer
This is the step people skip. An offer that is "subject to inspection" or "subject to manager approval" is a preliminary estimate, not a firm number. Note whether each offer is:
- Firm at the stated amount, or conditional on inspection
- Conditional on financing through that dealer
- Conditional on purchasing a specific vehicle from that dealer
A conditional offer can change after you have committed elsewhere, so treat the condition as part of the price.
Step 4: Note Each Offer's Expiration Date
Appraisals are typically time-limited because wholesale values move. An offer that expires in a few days forces a faster decision than one that holds for a week or more. Write the expiration next to each offer so you compare like with like.
Step 5: Subtract Payoff to Get Net Equity
Net equity equals the offer minus the payoff. Do this for each offer using the same payoff figure. If one dealer quotes a payoff that differs from your lender's quote, ask why before you compare.
Step 6: Compare the Total Deal, Not Just the Trade
The trade number is only one line. Build a side-by-side comparison of the full transaction for each dealer:
| Line item | Dealer A | Dealer B |
|---|---|---|
| Trade offer | ||
| Payoff | ||
| Net equity | ||
| New vehicle price | ||
| Documentation and title fees | ||
| Add-ons bundled into the deal | ||
| Sales tax treatment of the trade | ||
| Net amount financed |
That last row is the one that matters. A dealer with a slightly lower trade offer but lower fees and a cleaner tax treatment can produce the stronger net deal.
Step 7: Confirm Which Offer Is Tied to Dealer Financing
Some offers assume you finance through the dealer. If you plan to use outside financing or pay cash, confirm the trade offer still stands. An offer that shrinks when you decline dealer financing is not the same offer.
Step 8: Choose the Highest Net Deal
Pick the offer with the highest net equity after fees, conditions, and tax treatment, not the highest headline trade number. Then get the final figures on the purchase agreement before you sign.
Ask each appraiser which specific items reduced the offer and whether the offer is firm or conditional. Reconditioning line items are often negotiable if you have receipts showing recent tires, brakes, or battery work, and a firm offer is worth more than a conditional one at the same number.
How Trade Equity Changes Your Financing Costs
Trade equity works like a down payment, and that is the part most guides gloss over. Every dollar of equity you apply reduces the amount financed, which lowers the loan-to-value ratio and can improve the rate you qualify for. But the effect is easier to trust when you see the arithmetic, so here is the mechanism step by step.
The Four Numbers That Move
When you apply trade equity, four figures change together:
- Amount financed: the purchase price plus taxes and fees, minus your down payment and trade equity
- Loan-to-value (LTV) ratio: the amount financed divided by the vehicle's value (lenders often use the purchase price or a book value as the denominator)
- Monthly payment: recalculated on the smaller principal over the same term
A common pattern is that a lower LTV moves a borrower into a better rate tier, because the lender has more cushion if the vehicle must be repossessed and sold. That rate improvement compounds the savings from borrowing less.
A Worked Comparison
Consider two buyers purchasing the same vehicle for the same price, with the same term and the same lender rate tier before equity is applied. The only difference is that Buyer A applies equity from a paid-off trade and Buyer B finances the full amount.
| Line item | Buyer A (with equity) | Buyer B (no equity) |
|---|---|---|
| Vehicle purchase price | Same | Same |
| Trade equity applied | Yes | None |
| Amount financed | Lower by the equity amount | Full amount |
| LTV ratio | Lower | Higher |
| Monthly payment | Lower | Higher |
| Total interest | Lower | Higher |
The exact dollar difference depends on your price, rate, term, and equity amount, so run your own numbers with your lender's truth-in-lending disclosure.
Why the Rate Tier Matters as Much as the Principal
If applying equity moves you from a higher LTV band to a lower one, the rate you are offered can drop. That is a second, separate saving on top of the smaller principal. Ask the finance manager directly: "Does my LTV with this trade equity put me in a better rate tier?" If the answer is yes, get the before-and-after rate in writing on the disclosure.
The Negative-Equity Mirror Image
Negative equity runs the same math in reverse. If you owe more than the trade is worth, the shortfall is added to the new loan, which raises the amount financed, raises the LTV, and can push you into a higher rate tier.
Trade equity reduces the amount financed, which lowers your loan-to-value ratio and can improve your rate. A better appraisal has a compounding effect on total interest because it shrinks principal and can move you into a lower LTV band.
That is why competitive trade-in valuations for used vehicles for vehicle financing deserve real attention. A stronger appraisal is not just a better trade number. It changes the math on the entire loan.
Taxes, Fees, and Offer Conditions That Affect Net Trade-In Value
Fees and conditions to check:
- Documentation and title fees
- Dealer add-ons bundled into the deal
- Whether the offer expires
Lien release is the quiet one. If your lender holds the title, the dealer needs a payoff and a release before the title transfers.
At Rusty Eck Ford, we put the trade figure, payoff, fees, and taxes on one sheet so you can see the net number before you commit.
Frequently Asked Questions
What do dealerships use to value vehicles?
Dealerships combine several data sources: wholesale auction results, regional retail listings for comparable vehicles, vehicle history reports, and a physical inspection. They start from market value, subtract estimated reconditioning costs and a margin for risk, and arrive at an offer. The FTC notes that trade-in value depends on condition, mileage, and local demand. Asking for the specific comparables behind an offer helps you judge whether it is competitive for your vehicle.
How can I tell whether a trade-in offer is competitive?
Get at least two independent appraisals and compare them on a net basis, not just the headline number. Subtract any payoff quote, fees, or conditions attached to each offer. An online estimate from a used car trade-in value estimator gives you a baseline range. If one dealer is significantly higher, ask what assumptions they used about condition and reconditioning. A competitive offer should be within a reasonable band of wholesale market data and reflect your vehicle's actual condition.
How does trade-in equity affect an auto loan?
Trade-in equity is the difference between your vehicle's appraised value and your remaining loan balance. Positive equity can serve as a down payment, reducing the amount financed and potentially lowering your monthly payment and total interest. Negative equity gets rolled into the new loan, increasing the amount financed and the loan-to-value ratio. The FTC warns that a dealer's promise to pay off your trade-in loan does not eliminate the debt if the balance exceeds the vehicle's value, so confirm how any shortfall is handled.
Should I get a trade-in appraisal before applying for vehicle financing?
Yes. An appraisal before you apply gives you a firm equity figure to discuss with the finance office. The FTC's Auto Buyer Study found that some interview participants researched their trade-in vehicle's value before visiting a dealer, which supports a more informed negotiation. Knowing your payoff quote and appraised value in advance lets you see how the trade affects the amount financed and monthly payment rather than learning it at the end of the process.
Trading in a financed vehicle gets complicated fast, and one unclear number can cost you real money. Rusty Eck Ford has handled trade-ins and financing for drivers across the Wichita area since 1953, with on-site financing, written appraisals, and a team that shows you the math. Schedule a test drive and bring your payoff quote. We will walk you through the appraisal, the equity, and the final numbers line by line.