 how-to
Are New Ford Truck Financing Deals Worth It in 2026?
Last Updated: November 4, 2026
Quick Summary
Ford truck financing deals in 2026 are worth it only when you compare the total cost of the loan, not just the headline rate. A low APR can be offset by a longer term, lost cash-back rebates, or fees added to the amount financed. Check whether the offer applies to your exact trim and term before you count on it.
- Compare total cost, including all payments plus the down payment, not just the monthly payment.
- A 72-month offer at a low rate can cost more in total interest than a 60-month offer at a slightly higher rate.
- Ask whether the advertised APR can be combined with any cash-back rebate, since many offers cannot be stacked.
- Confirm the offer covers your specific model, trim, term, and credit tier, and get the terms in writing.
- Get pre-approved by a lender first so you can compare your real rate against the dealer's advertised offer.
Table of Contents
- What the Current 2026 Ford Truck Financing Offers Look Like
- Comparing APR, Cash Back, and Loan Terms
- Ford F-150 0% Financing for 72 Months: What to Verify
- Ford Truck Loan vs. Lease: Which Costs Less Over Time
- Ford Financing Offer Eligibility and Credit Considerations
- Estimating Your Monthly Payment on a New Ford Truck
- Checking Current Offers Before You Visit Rusty Eck Ford
- Frequently Asked Questions
Ford truck financing deals in 2026 can look very attractive on paper, but the headline rate rarely tells the whole story. Buyers in Wichita regularly ask whether a low APR is worth chasing. The short answer is that it depends on the total cost of the loan, your credit, and whether the offer applies to the truck you actually want. This guide walks through what to check before you sign.
What the Current 2026 Ford Truck Financing Offers Look Like
Recent 2026 deal roundups show a wide spread in advertised financing. Those listings are national roundups, so the rates do not guarantee what any single buyer will receive.
Offers are also packaged differently. Some combine a low rate with cash back, while others advertise a low rate alone. The right financing structure depends on how you plan to use the truck.
Comparing APR, Cash Back, and Loan Terms
A low APR and a cash-back rebate are not the same thing, and they do not always help you equally. A rebate lowers the amount you finance, while a lower APR reduces the interest charged over the life of the loan. Which one saves more depends on the size of the rebate, the loan term, and the price you negotiate. The only reliable way to compare them is to run the total cost of each scenario, not just the monthly payment.
Start by asking the dealer for four numbers on every offer: the total amount financed, the APR, the loan term in months, and the monthly payment. Then add the down payment and any fees to see the full out-of-pocket cost. A longer term lowers the monthly payment but usually means paying more interest overall, so a 72-month offer at a low rate can cost more than a 60-month offer at a slightly higher rate (How do I compare auto loan offers?).
A simple way to compare is to build two or three scenarios side by side. For each one, write down the negotiated price, the down payment, the rebate (if any), the APR, the term, and the total of all payments plus the down payment. The scenario with the lowest total cost is usually the better deal, even if its monthly payment is higher. Buyers who focus only on the monthly payment can overlook a meaningful amount of extra interest over the life of the loan.
Incentive stacking is where the fine print matters most. Many advertised APR offers cannot be combined with cash-back rebates or bonus cash, and some require you to finance through the manufacturer's captive lender to qualify. Before you choose, ask the finance manager directly: Can this APR be combined with the rebate? Does the offer require a specific lender, trim, or model? Does it expire on a set date? Get the answers in writing on the buyer's order.
Watch out: a dealer may quote a low APR that assumes a shorter term or a larger down payment than you planned, so confirm that the rate applies to the exact term and down payment you intend to use.
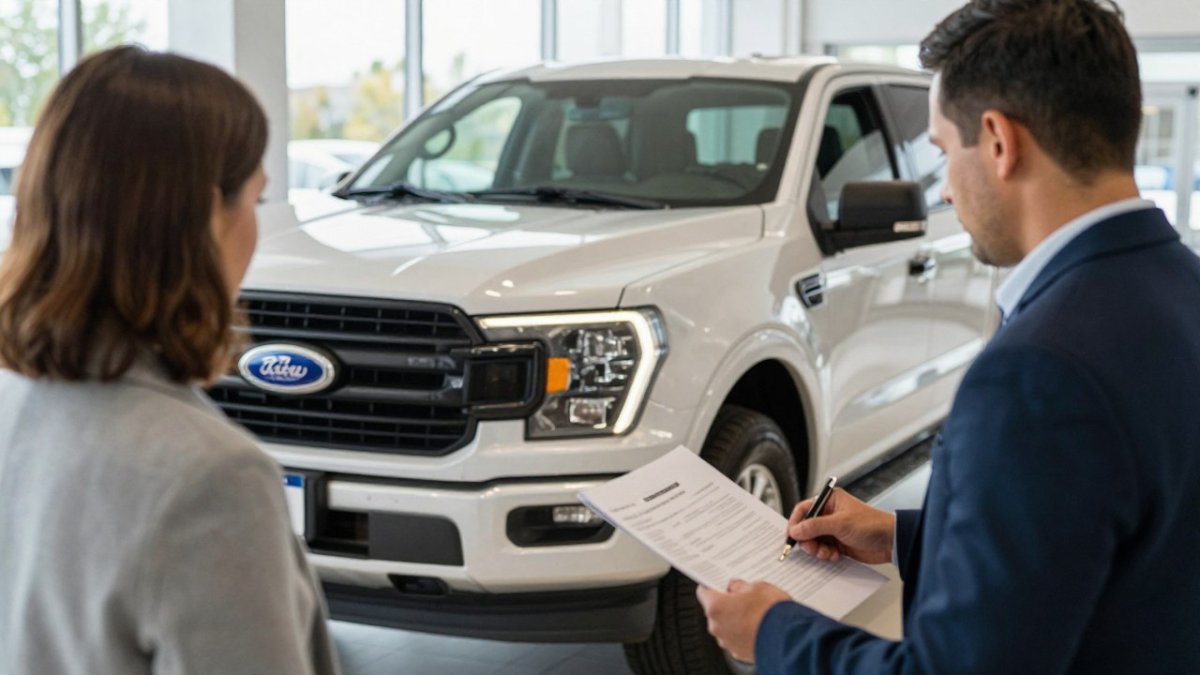
!Wichita-area buyer reviewing financing paperwork with a salesperson beside a new Ford pickup on a dealership lot
The table below compares the main financing factors covered in this section, so you can check each one against the offers you receive.
| Factor | What to check | Why it matters |
|---|---|---|
| Total amount financed | Negotiated price minus down payment | Sets the base for interest charged |
| APR | Rate tied to your exact term | Drives total interest over the loan |
| Loan term | Months stated on the offer | Longer terms lower payments but raise total cost |
| Cash-back rebate | Whether it can combine with APR | Lowers amount financed; may conflict with low APR |
| Fees and taxes | Itemized on the buyer's order | Often added to the amount financed |
| Total cost | Payments plus down payment | Best measure for comparing scenarios |
Ford F-150 0% Financing for 72 Months: What to Verify
Any financing offer you see should be checked for its exact term, whether it is 60 or 72 months, and whether it applies to your trim.
Before you rely on a zero-percent or near-zero offer, confirm three things: the models and trims covered, the length of the term, and whether the rate requires you to give up a cash rebate. Ask for those details in writing.
Ford Truck Loan vs. Lease: Which Costs Less Over Time
A loan builds equity because you own the truck at the end. A lease usually means lower monthly payments but no ownership, and you may pay for mileage or wear beyond the agreed limits.
If you drive a lot of miles or keep trucks for many years, a loan often costs less over time. If you prefer a new truck every few years and drive a predictable number of miles, a lease may fit better. Run the total payments for each path before deciding.
Ford Financing Offer Eligibility and Credit Considerations
Advertised rates are typically available only to qualified buyers, and that phrase does a lot of work. Lenders generally consider credit history, income, down payment, and the vehicle itself when they approve a loan (How does a lender decide what interest rate to offer me on an auto loan?). A buyer with strong credit may qualify for the advertised rate, while another buyer may be offered a higher one. Understanding how that decision is made helps you judge whether an advertised offer is realistic before you visit.
Most lenders sort approved buyers into credit tiers, and the advertised APR usually reflects the top tier. Ask the finance manager which tier the advertised rate requires and what credit profile typically falls into it. You do not need an exact score to have a useful conversation, but knowing whether you are likely to land in the top tier tells you whether to plan around the headline rate or a higher one.
A larger down payment can change the outcome. It reduces the amount financed and may move an approval into a better tier or a lower rate. If you are close to a tier boundary, ask whether increasing your down payment would change the approved rate or the monthly payment. The same applies to the loan term: shorter terms often carry lower rates but higher payments.
Before you rely on any advertised offer, verify four things in writing: the models and trims covered, the term length, the credit tier required, and whether the rate requires you to give up a cash rebate. A common pattern is for a headline rate to apply only to a specific trim and term, so confirm that the truck you want matches the offer.
A practical step-by-step process helps here. First, check your credit report for errors before you apply, since a reporting mistake can push you into a lower tier. Second, get pre-approved by a lender so you know your real rate and budget. Third, compare that pre-approval against the dealer's advertised offer. Fourth, confirm eligibility for the specific model, trim, and term you want. Fifth, ask for the itemized buyer's order so the rate, term, and fees are all visible before you sign.
Watch out: an advertised rate that requires a specific lender, trim, or term may not apply to the truck you actually want, so confirm eligibility for your exact configuration before you count on the offer.
Estimating Your Monthly Payment on a New Ford Truck
To estimate a monthly payment, you need the price you agree to pay, your down payment, the APR, and the loan term. Multiply the amount financed by the monthly interest rate, then add the principal divided by the number of months. A spreadsheet or the dealer's calculator can do this quickly.
Keep taxes, title, registration, and fees in mind. These are often added to the amount financed, which raises your payment. Ask for an itemized buyer's order before you commit.
Checking Current Offers Before You Visit Rusty Eck Ford
Offers change often, and some expire on a set date. Check the current offers on the Rusty Eck Ford website before you visit, and confirm that the model, trim, and term match what you are considering. The Rusty Eck Ford Black Friday event page lists current deals and incentives on popular Ford models, which can help you compare before you come in.
If you are weighing a shorter-term loan, you may want to see the current Credit Union of America financing promotion available during the dealership's August 2026 flash sale, which offers qualified buyers 4.59% APR. For a side-by-side look at Maverick, Ranger, F-150, and Super Duty models, the Ford truck buying guide can help you match the truck to your needs. Bring your budget, your target monthly payment, and your questions, and the team at Rusty Eck Ford can help you work through the numbers.
Frequently Asked Questions
Is Ford offering 0% financing for 72 months?
Ford offers vary by model, region, and dates. Offers vary, so confirm current terms directly with the dealer before assuming any particular rate or term applies.
What Ford trucks have special financing offers right now?
Published roundups list special financing on several 2026 Ford trucks. Some offers combine a low APR with cash back. Because listings are national and change often, check which models and trims qualify with the dealer before you plan a purchase.
Are Ford financing offers available to all buyers?
No. Advertised rates generally apply only to qualified buyers who meet credit approval and other conditions, and eligible models and trims vary. A rate shown in a deal roundup does not guarantee the rate you will receive. Ask the dealer which terms apply to your credit profile and the specific vehicle.
How do I compare a Ford truck loan with a lease?
Compare the total cost of each option, not only the monthly payment. A loan builds ownership equity over the financing term, while a lease typically offers lower payments for a set period with mileage limits and end-of-term charges. Review each option's terms, down payment requirements, and total cost side by side.