 how-to
How Long Dealership Financing Takes, Step by Step
Last Updated: November 6, 2026
Quick Summary
Dealership financing usually takes a few hours to a few business days. The first lender response often comes within minutes to hours, contract signing takes one to two hours at the desk, and final funding can take a few business days after you drive off.
- Gather pay stubs, proof of residence, insurance, and your license before arriving to avoid delays.
- Initial lender response often arrives within minutes to a few hours.
- Contract signing usually takes one to two hours once terms are set.
- Funding and final paperwork can continue for a few business days after you drive off.
- Ask whether your approval is conditional and what must clear before funding.
Table of Contents
- How Long Dealership Financing Usually Takes
- Step 1: Gather Your Documents Before You Arrive
- Step 2: Submit Your Application and Wait for Lender Review
- Step 3: Handle the Paperwork and Contract Signing
- Step 4: Understand Conditional Approval and Funding
- How to Speed Up Car Loan Approval
- Common Delays and What to Ask the Finance Office
- Your Next Step: Schedule a Test Drive and Start Your Application
- Frequently Asked Questions
Most car buyers in Wichita expect to leave the dealership with keys in hand the same day. Financing rarely works that way. How long dealership financing takes depends on your credit profile, the lenders the finance office contacts, and how complete your paperwork is when you arrive. Some applications return a first answer within minutes, while others take a few business days to fully clear. Knowing the steps ahead of time lets you plan your visit and avoid surprises at the finance desk.
This guide walks through each stage in order, so you know what to expect from application to signed contract.
How Long Dealership Financing Usually Takes
Dealership financing usually moves in stages, and each stage has its own clock. The first answer from a lender can arrive quickly, but a finished loan takes longer. Approval, contract signing, funding, and finalization are separate milestones, and people often confuse them.
- Initial lender response: Often within minutes to a few hours
- Approval and terms review: Commonly the same day, though some lenders need more time
- Contract signing: Usually one to two hours at the desk, once terms are set
- Funding and final paperwork: Can take a few business days after you drive off
Weekend and holiday visits often stretch these times, since lenders may not process files until the next business day. Timing also varies by lender type.
The table below summarises how long each stage of dealership financing typically takes, as described above.
| Stage | Typical timing | Note |
|---|---|---|
| Initial lender response | Minutes to a few hours | First answer can arrive quickly |
| Approval and terms review | Commonly the same day | Some lenders need more time |
| Contract signing | One to two hours | Once terms are set |
| Funding and final paperwork | A few business days | Can continue after you drive off |
Step 1: Gather Your Documents Before You Arrive
Gathering documents before you visit is the single most effective way to shorten the process. Missing paperwork is one of the most common reasons a file gets paused, and a paused file can add a day or more while the finance office waits on you. The right checklist depends on your situation, so use the list below that fits you rather than a one-size-fits-all set.
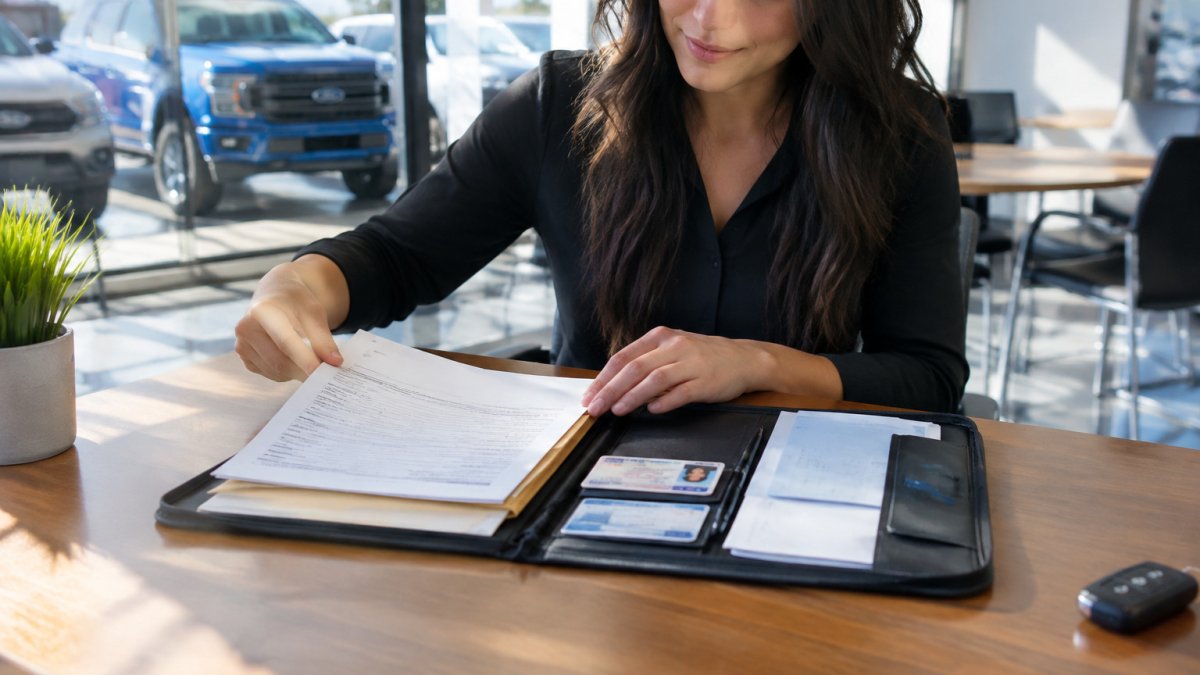
If you are a standard employed buyer:
- Valid driver's license: Confirms your identity
- Recent pay stubs: Usually the last two to three months, to show income
- Proof of residence: A utility bill or lease showing your current address
- Proof of insurance: Needed before you can drive the vehicle home
- Employment details: Employer name, address, and phone number so the lender can verify
If you are self-employed or a gig worker:
- Recent tax returns: Often the last one to two years, since pay stubs may not exist
- Bank statements: Several months showing consistent deposits
- Business license or 1099s: Helps the lender confirm income sources
- Profit-and-loss summary: A simple one-page summary can speed underwriting when income varies month to month
If you have thin or limited credit:
- Proof of steady income and residence: Lenders lean harder on these when the credit file is short
- A larger down payment plan: Have your numbers ready so the finance office can structure the deal
- Co-buyer information: If you plan to add a co-signer, bring their details too, since their file will also be reviewed
If you are trading in a vehicle:
- Title or payoff information: The lender or dealership needs to confirm ownership and any existing loan
- Loan account details: Lender name, account number, and payoff contact if the trade is financed
- Registration and current mileage: Speeds the appraisal and paperwork
Watch out: A common pattern is a buyer who brings pay stubs but not proof of residence, or a self-employed buyer who brings bank statements but no tax return. Either gap can pause the file while the finance office waits on a document, so pack everything in one folder before you leave home.
Having everything in one folder lets the finance office submit your application without waiting on you. If you are unsure what applies to your situation, call the finance office before your visit and ask which documents they want for your borrower type.
Step 2: Submit Your Application and Wait for Lender Review
Once you submit the application, the finance office sends your information to one or more lenders. Each lender runs a credit check and reviews your income and debt. This is called underwriting, and it is where most of the waiting happens. A hard credit inquiry typically appears on your report during this step.
Applying with several lenders at once can produce more offers, but each lender may review the file separately. Ask the finance office which lenders they are contacting and how long each usually takes. If you want to apply online before visiting, you can explore auto financing options directly from the dealership's website.
Keep your phone nearby during review. Lenders sometimes call to confirm employment or ask for a missing document, and a quick reply keeps the file moving.
Step 3: Handle the Paperwork and Contract Signing
After a lender approves your application, the finance office reviews the loan terms with you. These include the interest rate, the monthly payment, the loan length, and the total amount financed. Read each figure before you sign. Ask questions about anything that is unclear.
The contract signing itself often takes one to two hours. You will sign a retail installment sale contract and several disclosure forms. Make sure the numbers on the contract match what you agreed to on the sales floor. If you are unsure, ask the finance manager to walk through each line item.
Do not drive the vehicle home until the paperwork is complete and you have proof of insurance on file.
Step 4: Understand Conditional Approval and Funding
A conditional approval means the lender agreed to finance the loan, but only if certain conditions are met. Common conditions include verifying income, confirming your employment, or receiving a missing document. The deal is not final until these conditions clear.
Funding is the moment the lender sends the loan money to the dealership. Until funding happens, the sale is not complete from the lender's side. Occasionally, a lender declines to fund after you have taken the vehicle home. This is sometimes called a "spot delivery" problem, and the dealership may need to restructure the deal with a different lender or ask you to return the vehicle.
Ask the finance office directly whether your approval is conditional and what each condition requires. Clear answers early prevent problems later.
How to Speed Up Car Loan Approval
Several simple steps can reduce how long you wait:
- Bring complete documents: Missing items cause the most delays.
- Check your credit report first: Look for errors that could lower your score.
- Know your budget: A clear monthly payment target makes term decisions faster.
- Pick your vehicle early: Lenders review the vehicle and price along with your application.
- Avoid new debt before applying: New accounts can change your debt-to-income ratio mid-review.
- Answer calls quickly: Lenders often need a quick confirmation.
Pre-approval can also help. Some buyers get pre-approved through a bank or credit union before visiting, which gives them a benchmark to compare against the dealership's offers. You can also get pre-approved through our auto loans page before you arrive.
Common Delays and What to Ask the Finance Office
Most financing delays come from a short list of causes: incomplete documents, a credit file that needs review, employment verification that takes time, or a lender that is busy. Weekend visits and holidays can add a day or more because lenders may pause processing until the next business day.
Know which milestone you are waiting on. Approval, contract signing, funding, and finalization are separate steps, and a delay at one does not mean the others are stuck. If the finance office says you are approved, ask whether that means the lender has issued final terms or only a conditional approval.
Understand conditional approval and stipulations. A conditional approval means the lender agreed to finance the loan only if certain conditions are met. Common stipulations include verifying income, confirming employment, proving residence, or receiving a missing document. The deal is not final until these clear.
What happens if the deal is unwound. Occasionally a lender declines to fund after you have taken the vehicle home. This is sometimes called a spot delivery problem. The dealership may need to restructure the deal with a different lender or ask you to return the vehicle.
How to check your application status. You can ask the finance office directly for a status update and for the name and phone number of the person handling your file.
Business-day, after-hours, and holiday effects. Lender processing generally follows business days. An application submitted Friday afternoon may not see lender review until Monday, and a holiday can push it further.
When a delay happens, ask these questions:
- Which lender is reviewing my application right now?
- Is my approval final or conditional, and what must clear before funding?
- What document or condition is still needed, and who is responsible for it?
- Has the lender funded the loan yet, or is the dealership still waiting?
- What is the expected timeline for a decision?
- If the first lender declines, do you have other lenders to try?
Some buyers also review current Capital One auto loan event options at the dealership to compare lender choices if their first offer is slow.
Your Next Step: Schedule a Test Drive and Start Your Application
Dealership financing usually takes a few hours to a few business days, depending on your documents, your credit profile, and the lenders involved. Preparing ahead of time is the best way to keep the process short and predictable.
When you are ready to move forward, you can browse used cars, trucks, and SUVs in Wichita and estimate payments online before you visit. Then schedule a test drive and bring your documents to start the application. Our team is glad to walk you through each step from the first conversation to the final signature.
Frequently Asked Questions
How long does it take to get approved for financing at a dealership?
Many dealership financing applications receive an initial response within minutes to a few hours, but that is not the same as a final decision. Lenders may still need to verify income, employment, or identity before approving the loan. Full approval often takes a few hours, and it can stretch to a few business days if documents are missing or the lender needs more information. Submitting a complete application with all required paperwork is the most reliable way to keep the process moving.
How long does dealership financing paperwork take?
The paperwork usually takes a while to finish, depending on how many documents the finance office must review and whether the buyer has everything ready. Reviewing the retail installment contract, the loan terms, and any add-on products takes time, especially for a first-time buyer. Arriving with your documents organized and asking questions as you go can shorten the time you spend in the finance office.
What can delay car loan approval at a dealership?
Common causes include missing pay stubs, unverified employment, an incomplete application, or a lender that needs extra review. Credit history questions and a limited credit profile can also slow underwriting. Delays are more likely late in the day, on weekends, or near holidays, when lender staff are reduced. Asking the finance office which item is outstanding helps you resolve it faster.
Can you drive a car home before financing is finalized?
Some buyers drive a vehicle home before the loan is fully funded, but that depends on the dealership's policy and the lender's terms. Approval, contract signing, funding, and finalization are separate milestones, and the deal can change if a condition is not met. Ask the finance office whether your deal is final and what happens if the lender declines the terms, so you understand your obligations before you leave.